



How Lenders Reduce Loan Processing Time With Automation
Introduction
In many lending operations, a loan can spend more time waiting than being processed. An application sits until someone reviews it. Staff wait for documents or outside data. Information moves between systems. An exception lands in a queue and needs someone to pick it up. Each delay adds time between application and decision. At higher volumes, the problem gets harder to contain. Processors carry more work, application queues grow, and borrowers wait longer for an answer. Some may leave before the lender reaches a decision.
Speed, however, is not simply about approving loans faster. Lenders still need to verify information, apply credit policy, review exceptions, and keep accurate records. The opportunity lies in reducing the manual work and unnecessary waits around those decisions. Automation can help lenders do exactly that.
What Is Loan Processing Automation?
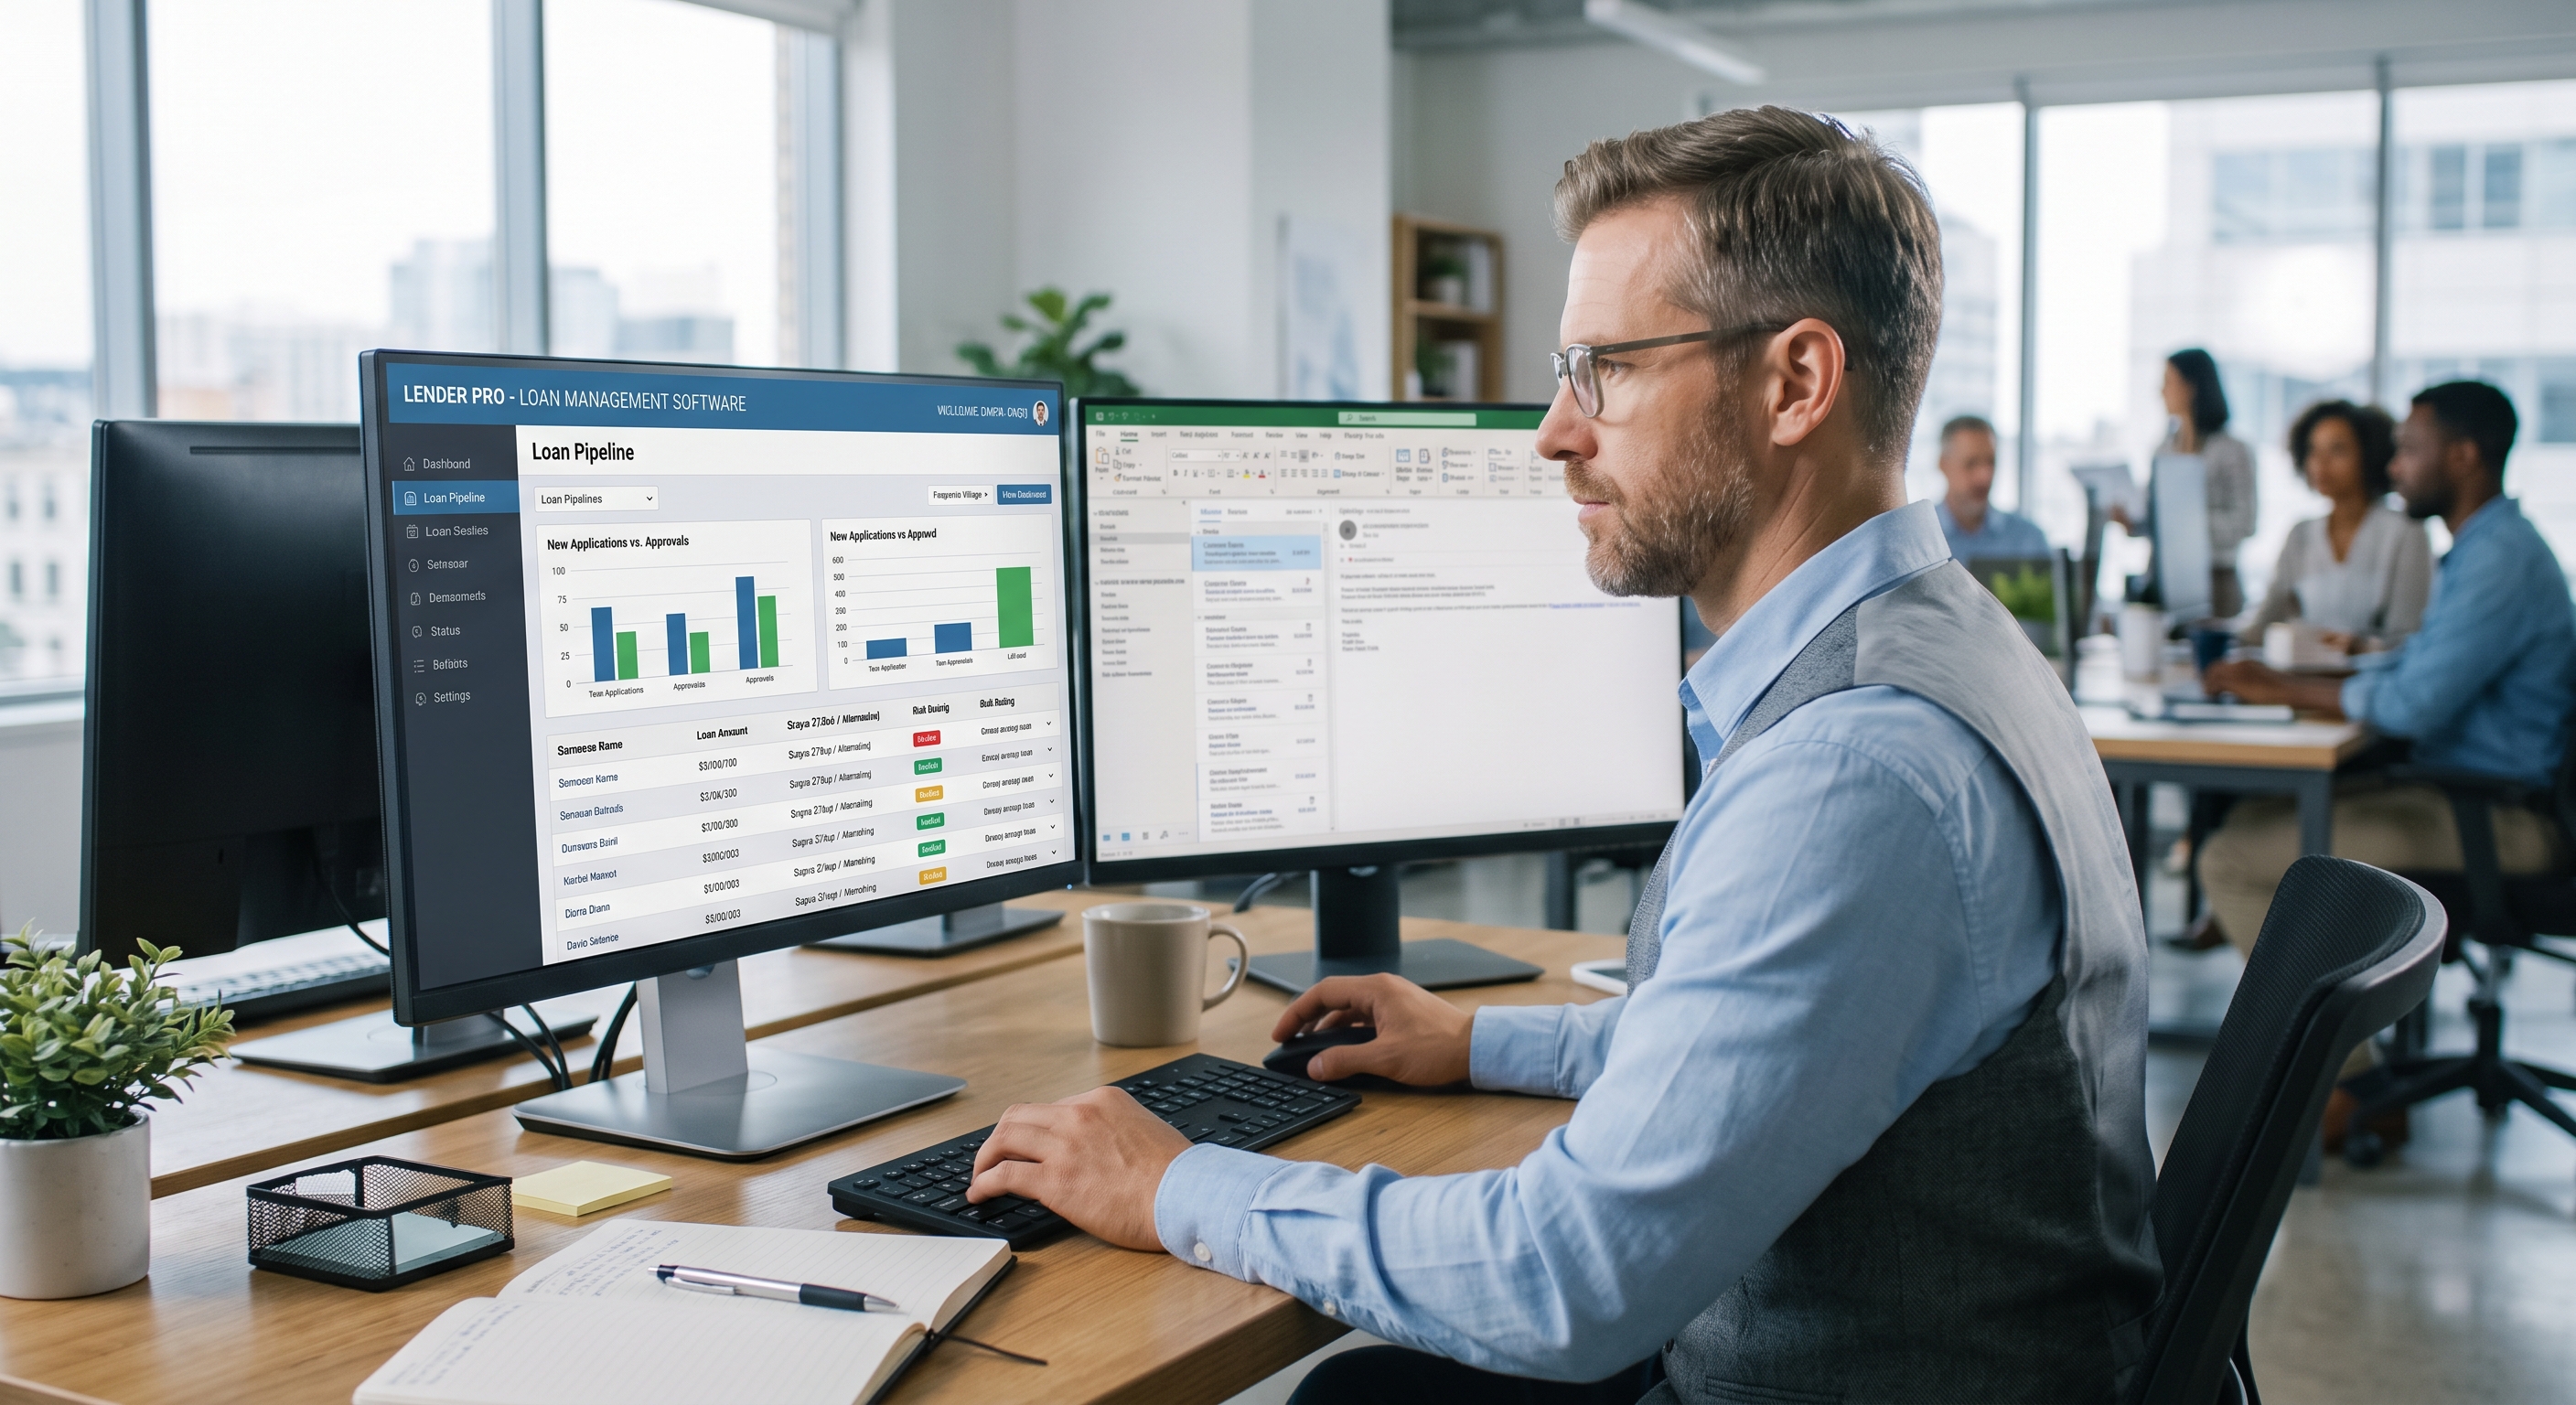
Loan processing automation uses loan processing software to carry out repetitive steps in the lending workflow with limited manual intervention. Depending on the lender’s setup, that can include collecting application data, requesting documents, verifying information, applying underwriting rules, routing exceptions, updating loan records, or moving an application to its next stage. By automating these routine tasks, loan processing software can help lenders create more consistent workflows, reduce manual work, and keep applications moving efficiently. Loan processing software can also connect different lending functions, allowing data to move more efficiently between application intake, verification, underwriting, funding, and servicing.
Loan Processing Digitization vs. Automation: What’s the Difference?
A lender may replace a paper application with an online form, but staff might still have to review the submission, enter information into another system, request data from outside providers, and manually send the application to underwriting. The information is digital, yet much of the underlying work remains manual.
Automation changes what happens after that information enters the system. An application can move through predefined workflows, trigger required checks, and reach the appropriate person or next stage based on the lender’s rules.
Human judgment still has a place. Loan underwriters can review exceptions or applications that require closer attention, while modern loan underwriting software handles the routine steps surrounding those decisions, helping underwriters work more efficiently and consistently.
Where Loan Processing Delays Actually Happen
Loan processing rarely slows down because of one major problem. Delays tend to build across smaller tasks as an application moves between people, systems, and stages.
Manual Data Entry
Staff may have to copy borrower information between systems or enter data received from another source. Each manual step takes time and creates another opportunity for errors that may need correction later.
Repeated Data Checks
Borrower information can be reviewed more than once when teams work across separate systems. A processor may check information another employee has already verified simply because the earlier work is not visible.
Document Collection
Missing documents can leave an application sitting in a queue. Staff may also spend time requesting files, following up with borrowers, reviewing submissions, and identifying incomplete information.
Waiting for External Data
Underwriting may depend on credit, identity, fraud, banking, or other third-party data. When those requests require separate actions or disconnected systems, the application can wait for information before moving forward.
Underwriting Handoffs
An application may be ready for underwriting but still wait for someone to review it. Manual assignment and unclear ownership can add processing time without adding anything to the credit evaluation itself.
Exception Handling
Some applications will fall outside standard rules or require additional review. Without a defined path for those cases, exceptions can remain unresolved in processing queues.
Approval and Funding Handoffs
An approval does not always move directly to funding. Final checks, documents, signatures, or internal handoffs may still need completion before funds can be released.
Individually, these delays may appear small. Across a high volume of applications, they can consume a significant share of the total processing time.
How Automation Speeds Up Loan Processing?
Advanced loan automation software reduces processing time by cutting manual work between stages of an application. Instead of waiting for staff to initiate every action, the workflow can move forward when predefined conditions are met.
Capture Application Data Once
Borrower information collected during the application should remain available as the loan moves forward. Underwriting, verification, document preparation, and other processes can work from the same record rather than requiring staff to enter the same information again. This removes repetitive work and reduces errors that could hold up the application later.
Trigger Data and Verification Checks
Credit, identity, fraud, banking, and other checks can begin when an application reaches the appropriate stage. Staff do not have to open another system and initiate every request themselves. Once the required information returns, the workflow can use it for the next step or flag the application for further review.
Automate Routine Underwriting Steps
Lender-defined rules can evaluate applications against established credit criteria as the required data becomes available. Straightforward cases can move toward a decision without waiting in the same queue as applications that need an underwriter. Credit policy and risk appetite still remain under the lender's control.
Route Exceptions to the Right Queue
Automation also needs a path for applications that cannot continue normally. Missing information, failed checks, or results outside configured criteria can route the case to the appropriate person or review queue. Staff can then focus on the issue instead of first determining why the application stopped moving.
Automate Documents and Workflow Actions
Routine processing should not stop every time an application reaches a new stage. For instance, a status change can start the next required action, such as requesting documents or notifying the team responsible for the next step. This keeps administrative work moving without waiting for someone to manually initiate each task.
Move Approved Applications Toward Funding
An approved application may still need documents, signatures, final checks, or other conditions completed before funding. Automation can move these tasks forward as each requirement is met instead of relying on staff to manage every handoff. Human review remains important when an exception or lending decision requires judgment.
Key Benefits of Automated Loan Processing
Reducing loan processing time affects how much work a team can handle, where employees spend their time, and how much control lenders have over the application pipeline.
Higher Application Throughput
When routine processing requires fewer manual actions, teams can handle more applications without adding the same amount of operational work. This becomes especially important when application volume rises, and existing staff must manage a larger pipeline.
Less Manual Work
Processors spend less time entering information, performing routine checks, and moving applications between stages. That leaves more capacity for borrower issues, complex cases, and other work that requires direct attention.
Faster Borrower Responses
Reducing waits between processing stages can shorten how long borrowers wait for an answer. Faster responses also give lenders a better chance of keeping qualified applicants engaged while they consider their options.
More Consistent Workflows
Configured workflows give applications a defined path through processing. Routine steps follow the lender's established requirements instead of depending on individual employees to remember and initiate every action.
Better Exception Management
Automation can separate routine applications from cases that need closer review. Underwriters and processors can direct more attention toward missing information, unusual risk signals, or other exceptions that require judgment.
Greater Workflow Visibility
A connected process makes it easier to see where applications are sitting and which stages repeatedly create delays. That visibility helps lenders identify bottlenecks and decide where further process changes may be needed.
Best Practices for Implementing Loan Processing Automation
Automation works better when lenders first understand the process they are trying to improve. Effective loan automation strategies should focus on identifying bottlenecks, reducing repetitive work, and improving workflow consistency before implementing automation. Automating a poorly designed workflow can simply make the same problems happen faster.
Map the Current Workflow First
Start by tracing an application from submission to funding. Identify which teams touch it, which systems they use, what information moves between them, and where manual actions occur. This creates a clear picture of the process before you change anything.
Find the Actual Bottlenecks
Look at where applications spend the most time waiting. The problem might sit in document collection, underwriting queues, external data requests, or internal handoffs. Actual processing data provides a better starting point than assumptions about where delays occur.
Start With Repetitive Work
Predictable tasks are usually stronger candidates for automation. Data entry, routine checks, status updates, and workflow routing can consume staff time without requiring much judgment. Removing that work gives employees more room to handle complex applications.
Define Exception Paths
A workflow also needs to account for cases that do not follow the expected path. Missing documents, unavailable data, failed checks, or unusual results should have a defined destination for review rather than leaving an application stalled.
Connect the Systems That Matter
External systems should provide information when the workflow actually needs it. Useful integrations can reduce the need for staff to switch platforms, retrieve data separately, and transfer it back into the application record.
Keep Human Review Where It Adds Value
Loan Underwriters still need control over cases involving uncertainty, policy exceptions, or additional investigation. Automation should reduce the administrative work surrounding those decisions rather than remove necessary judgment.
Measure the Result
Track processing time before and after implementation. Queue sizes, manual workload, exception rates, and application throughput can also show whether automation removed a real bottleneck or simply moved it elsewhere.
How Infinity Supports Loan Processing Automation
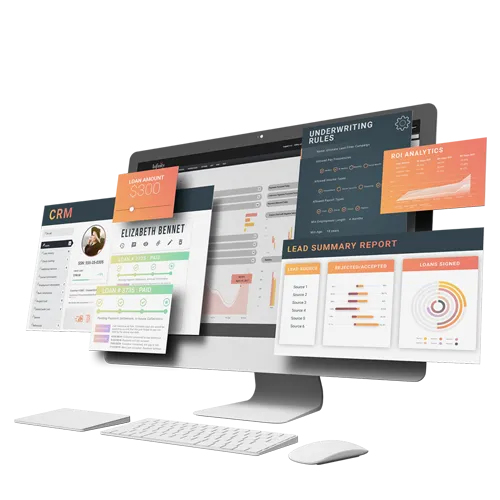
Infinity Software supports loan processing from application and underwriting through approval and funding. Lenders can automate routine workflows, manage borrower data and documents, apply configured underwriting rules, and route applications that need further review. Integrations with external systems also help bring required information into the workflow without repeated manual transfers. Application tracking gives teams visibility into where each file stands, reducing unnecessary handoffs and keeping applications moving toward a decision.
Conclusion
Faster loan processing starts with finding the time an application spends waiting rather than being evaluated. A digital application alone will not solve that problem, and automating every possible task is not the answer either. The bigger opportunity sits in the gaps between decisions. Manual data entry, repeated checks, unnecessary handoffs, and poorly routed exceptions can all add time without improving the lending decision itself.
Lenders that identify those delays first can apply automation where it has the most value. The result is a faster process without sacrificing the human judgment lending still requires.




 <