



Loan Underwriting vs. Loan Decisioning: Complete Comparison
Introduction: Loan Underwriting vs. Loan Decisioning
A borrower submits an application. The credit data comes back. Income has been verified. Risk factors have been evaluated. Everything needed to assess the application may already be on the table. Yet one question remains: what should the lender actually do with it?
This is where loan underwriting and loan decisioning are often treated as the same process. The confusion is understandable. Both rely on borrower data, lending criteria, and risk information. Automation has brought them even closer, with underwriting and decisioning capabilities often operating within the same workflow.
Their purposes, however, are different. Underwriting primarily evaluates the risk involved in extending credit. Decisioning uses relevant information and lender-defined rules to determine how an application should proceed.
The boundary can blur in practice. Understanding what each process is trying to accomplish makes the difference much easier to see.
What Is Loan Underwriting?
Loan underwriting is the evaluation process lenders use to analyze borrower risk before extending credit. Rather than deciding the final outcome of a file, underwriting examines financial data to determine how likely an applicant is to repay a debt according to the proposed terms. Loan underwriting software can help automate and streamline this evaluation by analyzing borrower information, applying predefined lending rules, and supporting consistent risk assessments.
What Does Loan Underwriting Evaluate?
The depth of evaluation depends on the loan product, internal policy, and regulatory requirements. Underwriting systems and human analysts typically examine several core financial indicators:
Credit History and Payment Behavior: Historical credit performance shows how reliably an applicant manages existing debt, highlighting past delinquencies, credit utilization, and public records.
Income and Capacity to Repay: Verified income sources are compared with proposed debt service to confirm the applicant has sufficient cash flow to cover monthly obligations.
Existing Financial Obligations: Current recurring debts, rent payments, and outstanding loans are tallied to calculate the borrower’s overall debt-to-income ratio.
Employment and Banking Stability: Bank account records and employment tenure confirm steady income streams, active account balances, and overall financial consistency.
Where Automation Fits Into Underwriting
Underwriting does not require an employee to manually evaluate every application. Automated systems can collect data, perform calculations, apply lender-defined criteria, and identify cases that need closer attention. Exceptions, missing information, or unusual risk signals can still move to an underwriter for review.
The process ultimately gives the lender a clearer view of risk. Depending on the workflow, the output might be a score, risk classification, eligibility finding, recommended outcome, or referral for further review. That information can then feed into the lending decision.
What Is Loan Decisioning?
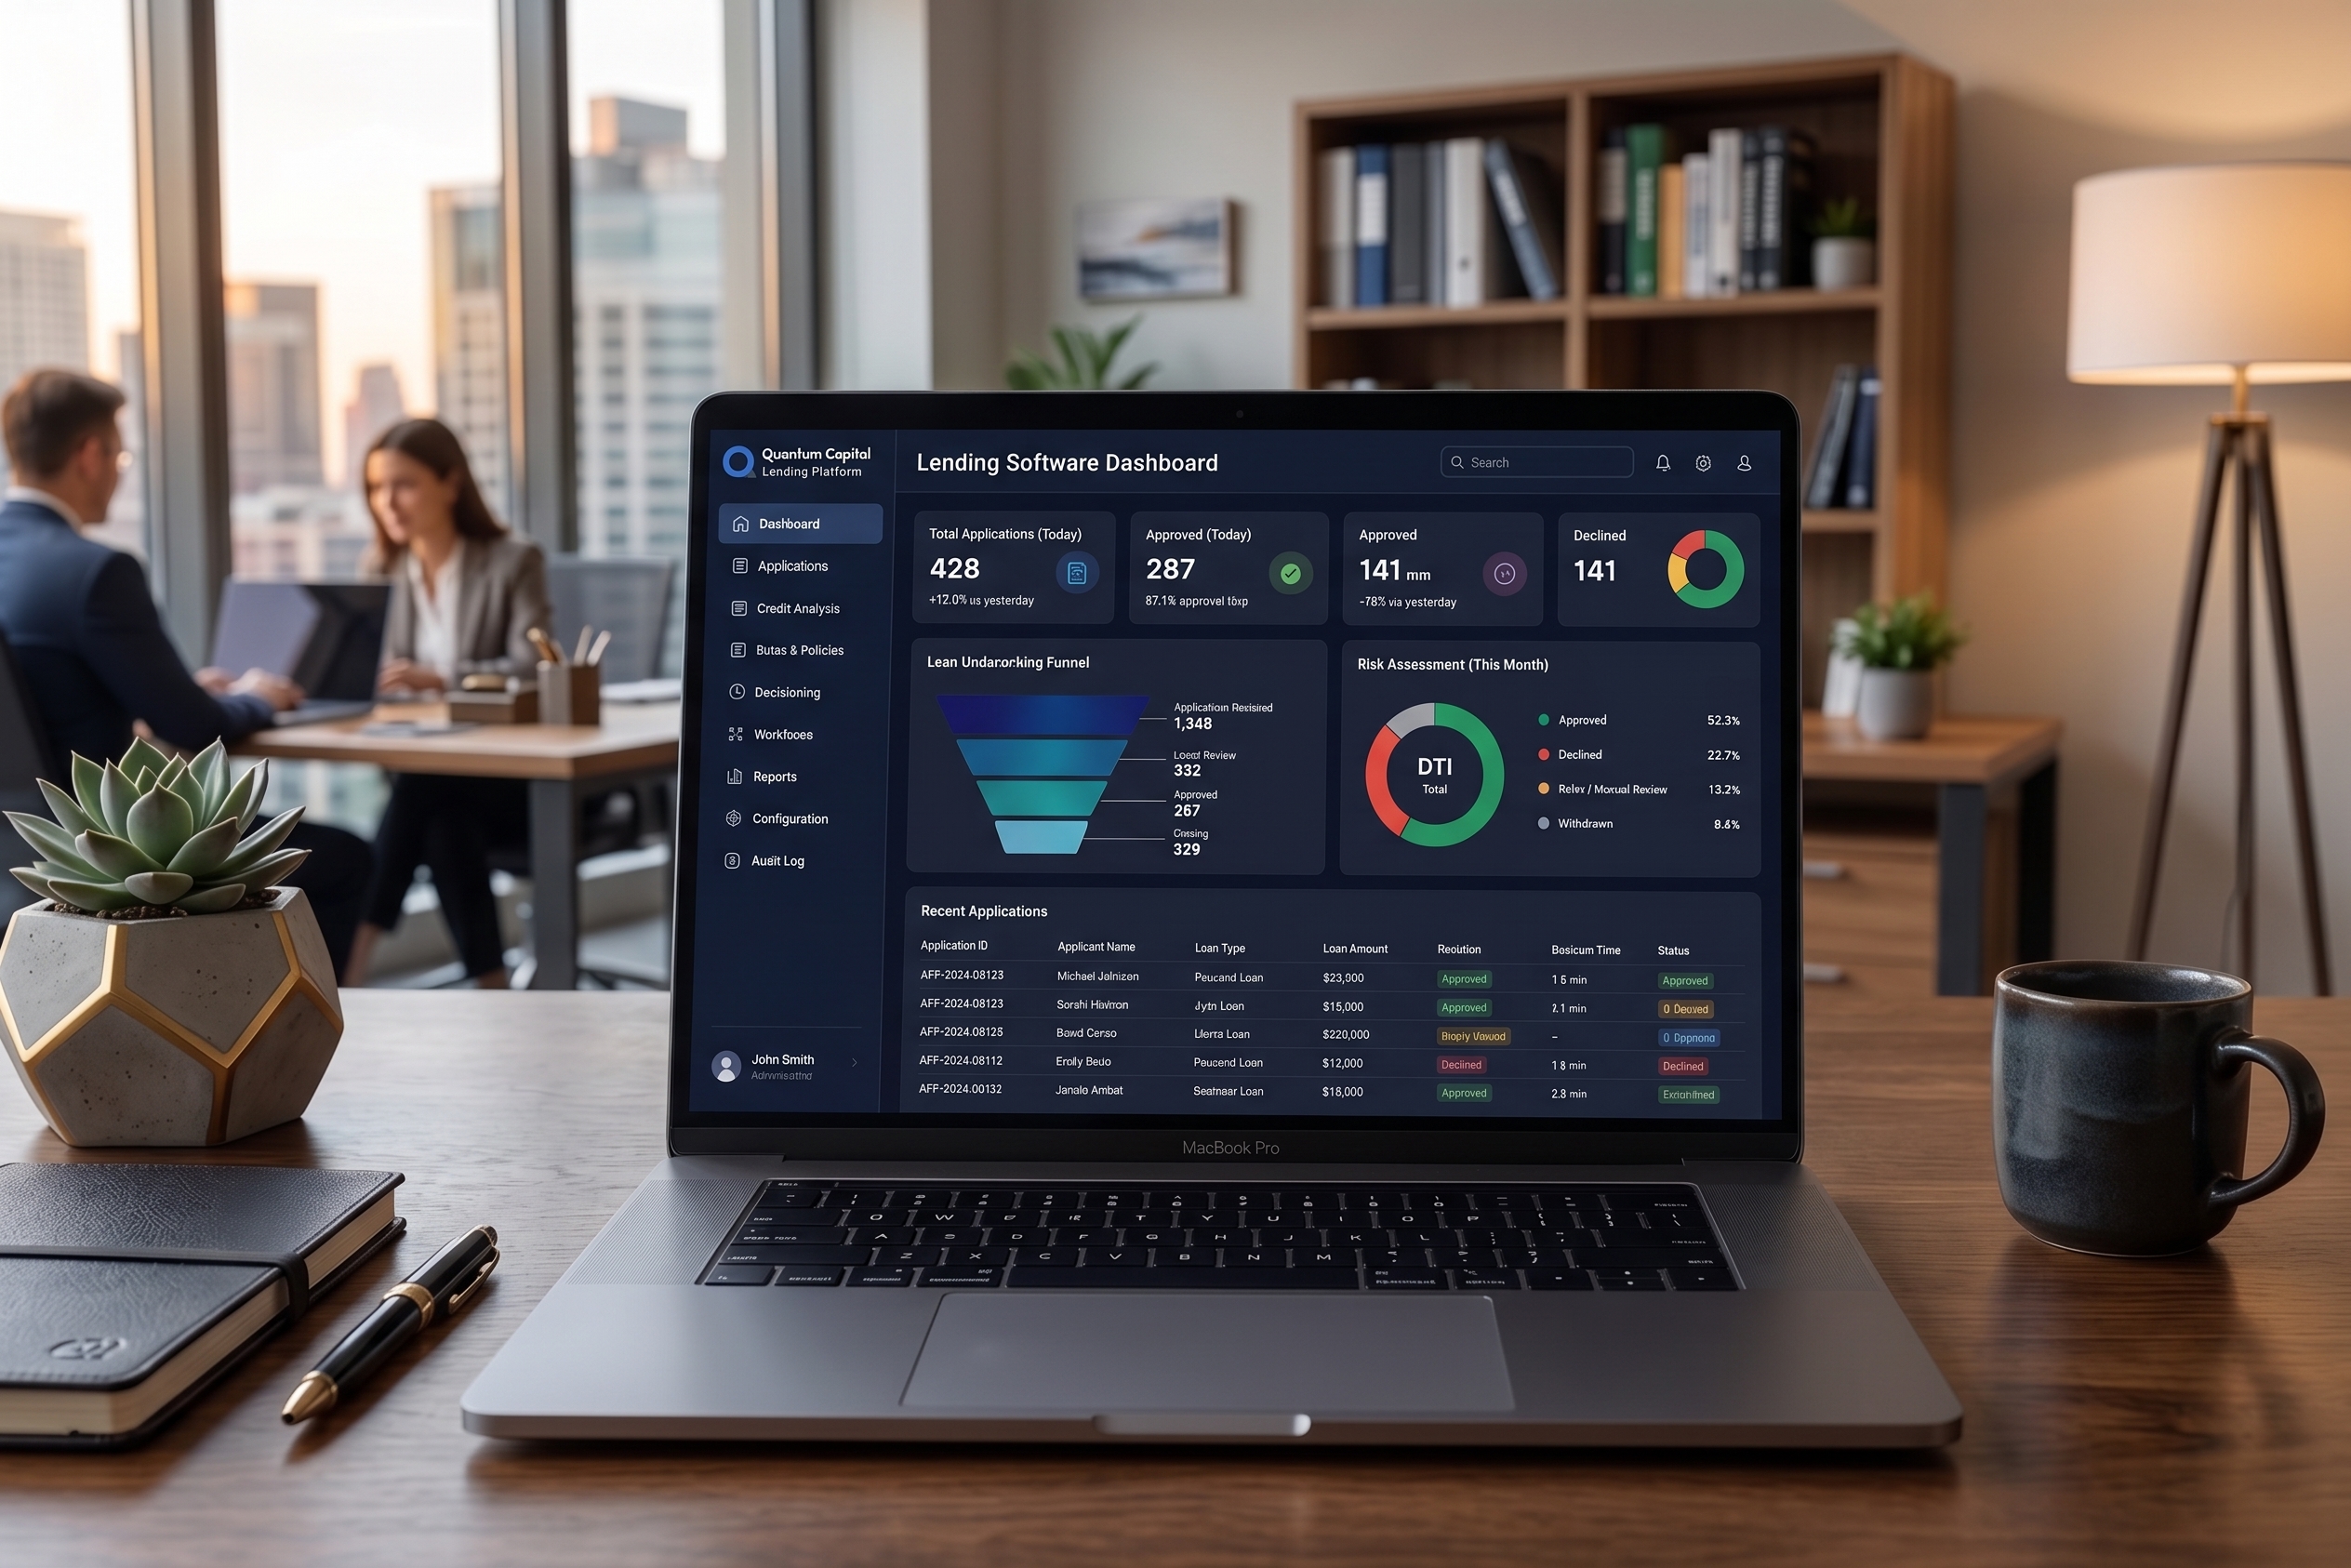
Loan decisioning is the process of determining what should happen to an application based on the information available to the lender. Loan decisioning engine software can use underwriting results, borrower data, verification findings, credit policy, and other lender-defined rules to determine the next action.
A decision does not always mean a simple yes or no. Depending on the lender and loan product, an application may follow several paths:
Approve
Decline
Manual Review
Additional Verification
Decisioning can also affect other parts of the offer or workflow, including:
Loan Amount: Determine whether the borrower qualifies for the requested amount or another amount under the lender’s rules.
Pricing and Terms: Apply eligible rates, fees, or repayment terms based on configured criteria.
Application Routing: Send cases to the appropriate workflow when additional review or action is required.
Verification Requirements: Request further information when existing data is not enough to proceed.
Where a Decision Engine Fits
A loan decision engine applies the lender’s configured logic to the information entering the decision process. For example, an application may need to satisfy risk thresholds, pass required verification, and meet product criteria before it can follow an approval path.
The engine can execute those rules consistently and route the application accordingly. It does not decide how much risk the lender should accept. The lender still controls credit policy, approval thresholds, and risk appetite.
Key Differences Between Loan Underwriting and Loan Decisioning
Loan underwriting and decisioning can use the same borrower data, rules, and risk signals. They may also happen within the same platform and within seconds of each other. That overlap makes the terms easy to confuse. The distinction becomes clearer when you look at what each process is trying to determine.
Area | Loan Underwriting | Loan Decisioning |
Primary Purpose | Evaluate the risk involved in lending | Determine what happens to the application |
Core Question | How risky is this loan? | What action should we take? |
Inputs | Credit, income, banking, borrower, and other risk data | Underwriting findings, borrower data, credit policy, and decision rules |
Typical Output | Risk assessment, score, eligibility finding, or review result | Approve, decline, refer, route, or another configured action |
Human Involvement | Underwriters may review complex or uncertain cases | Staff may handle exceptions and referred applications |
Automation | Risk checks and parts of the evaluation can be automated | Outcomes, routing, and other decision actions can be automated |
Evaluation vs. Action
Underwriting focuses on understanding the risk presented by the borrower and the proposed loan. Decisioning takes relevant information and determines which action fits the lender's established criteria. In simple terms, one builds the risk picture, while the other determines the application’s path.
Risk Analysis vs. Decision Logic
An underwriting process may examine credit history, income, existing obligations, banking information, and other relevant signals. Decisioning takes those findings and applies lender-defined thresholds, product requirements, and approval rules to determine what happens next.
Where the Two Processes Overlap
The boundary becomes less obvious in automated lending. An underwriting system may apply rules and produce a recommended or final outcome. A decision engine may also perform calculations or evaluate risk signals before choosing a path.
For that reason, underwriting and decisioning should not be treated as two completely separate technologies. Their functions can overlap. The more useful distinction is operational: underwriting develops the lender’s understanding of risk, while decisioning determines how the application proceeds under the lender’s rules.
How Loan Underwriting and Decisioning Work Together
Separating risk analysis from action logic becomes clear when tracking an application through the lending pipeline:
Application → Data Collection → Underwriting → Risk Evaluation → Decisioning → Approve / Decline / Review
Application and Data Collection
A borrower submits basic personal details through an intake portal or counter register. External data pipelines pull credit histories, confirm banking activity, verify identity credentials, and run fraud checks to populate the master file.
Underwriting Evaluates the Application
System tools examine the aggregated financial profile against core risk metrics. Automated verification engines measure debt ratios and income stability, while human underwriters investigate unusual document gaps or past payment discrepancies on complex files.
Decisioning Applies Lending Logic
Calculated risk outputs flow directly into the decision engine. Configured business rules check these underwriting findings against current credit policies, desired loan terms, product availability, and regulatory limits to determine the exact next step.
The Application Moves Forward
Executing the rule logic triggers immediate action. The platform can grant automated approval, issue a formal declination notice, request additional bank documentation, or route borderline cases to senior managers for exception review.
A simple practical example illustrates the core difference between the two functions:
Discovering that an applicant maintains a 680 credit score and zero recent delinquencies represents an underwriting finding.
Determining that this specific credit profile qualifies for a $5,000 unsecured installment loan at 12% interest under your institution's current lending policy represents a decisioning outcome.
Underwriting establishes facts regarding applicant risk. Decisioning executes business rules based on those facts to advance the application.
Where Infinity Fits
Infinity Software connects underwriting and decisioning with the broader loan workflow. Lenders can use borrower and external data, configure credit criteria and decision rules, and automate routine evaluations. Applications that require closer attention can move to manual review.
Once a decision is reached, the application can continue through the configured workflow toward approval and funding. This keeps risk evaluation, decisioning, and the next stage of the loan process connected within the same system.
Looking Forward
There is a thin line between loan underwriting and loan decisioning. Remove that line, and the two can easily look like the same process. The difference becomes clearer when you focus on purpose. Underwriting helps lenders understand the risk behind an application. Decisioning determines what happens next under the lender’s rules.
Modern lending technology may bring both processes into the same workflow, but their roles still matter. Understanding that distinction helps lenders build clearer credit policies, decision rules, and review paths.




 <