



Installment Loan Management Software Challenges & Solutions
Lending does not begin when an applicant walks in. It does not even start when the loan is funded. In fact, funding is often the stage where real loan management comes in. Loan management requires ongoing attention until the borrower repays all borrowed capital. Similarly, installment loans require consistent evaluation and monitoring across multiple repayment cycles. You have to schedule payments, maintain borrower records, and avoid delinquency. If overlooked, these factors create recurring operational demands. What adds to these operational headaches are manual processes and disconnected systems. When data is scattered across sheets and systems that hardly communicate, it becomes difficult to manage these tasks at scale.
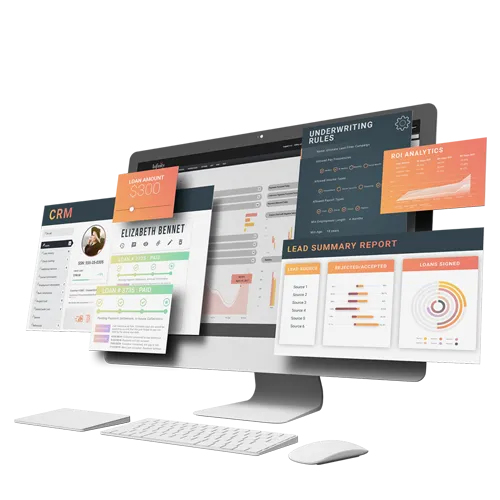
With installment loan management software, however, you don’t have to shuffle sheets or manually inspect every system involved in installment lending. The software keeps data in a single platform, allowing lenders to have complete insight into portfolio performance.
What Is Installment Loan Management Software?
Installment loan management software is primarily focused on managing loans after funding. Lenders can handle repayment schedules; check outstanding balances; evaluate payment records; and update accounts. The software’s primary goal is to showcase accurate and organized servicing as borrowers make regular installments. It gives servicing teams a clearer view of each account and its repayment status.
Apart from that, the software also tracks missed payments, frequent delinquencies, or charge-offs. Loan management takes over once the loan is active. Some platforms cover both stages. Depending on its capabilities, Installment Lending Software may support the entire lending lifecycle, from initial application to final payoff.
Common Installment Loan Management Challenges and Their Solutions
It becomes difficult to manage the portfolio when installment loans are growing in the backend. With each surge in the pile of loan applications, several challenges may come up. This is because each account has different parameters to evaluate. Some have different repayment terms. Others have complicated repayment histories. We have extracted the most common challenges lenders face when processing installment loans.
1. Managing Complex Repayment Schedules
Challenge:
When systems rely on manual input to see every scheduled repayment, room for errors increases. Because installment loans come with different interest rates. Varied repayment frequencies. And lenders predefine loan terms. No two borrowers have the same loan terms or repayment history, let alone credit score. Even a small mistake can affect payment amounts, outstanding balances, and borrower records.
Solution:
But now lenders have an easy fix to overcome this lurking fear of errors in calculations. Installment loan management software, with its ability to align repayment schedules with loan terms, calculates balances when payments are posted or when changes are made to figures. As a result, this automation reduces manual dependency for every minor task and helps servicing teams maintain accurate accounts.
2. Tracking Payments and Outstanding Balances
Challenge:
Payment data is never static. It moves between systems. And since it travels across processors, banking systems, and servicing departments, it is almost impossible to maintain records that actually match what is recorded in the system. And when that mismatch in records happens, employees have to look for discrepancies. From borrowers' end, they may also experience having incorrect account balances.
Solution:
The immediate solution to curb these gaps is to shift to connected systems. With manual intervention, that connection between different systems becomes a delusion on the lender's part. Installment loan management software captures transaction statuses and immediately updates loan records when payments are confirmed. Not only does such communication give lenders a clearer view of collected payments and outstanding balances, but it also reduces the time spent correcting records.
3. Delinquency and Collections
Problem:
A missed payment goes cold fast. When account data lags, collectors work blind. They cannot tell which borrower slipped yesterday and which one is gone for good. Every day of delay burns time, bleeds recovery costs, and turns soft debt hard.
Solution:
Installment lending software counts the days past due. It flags troubled accounts the morning they turn. Workflows push reminders, queue priority calls, and direct collectors toward the debts they can still save. The team acts early. They work in order. And above all, they stay ahead of the loss.
4. Accurate Borrower Records
Problem:
Borrower information is constantly changing. Phone numbers become outdated. People make partial payments or change banks midway through a three-year note. When staff logs these changes across separate spreadsheets and siloed software, the truth splinters. One agent sees a paid balance; another sees a default. Servicers call the wrong numbers, dispute cleared checks, and lose borrower trust. Bad records create unnecessary fights, and fighting costs money.
Solution:
A single source of truth l holds the loan from start to finish. Good Installment loan management software anchors contact info, daily balances, and payment logs to one central file. When a borrower pays or updates an address, every screen shows the change at once. Servicers pull the file and see the facts immediately. Nobody hunts through dead files, nobody guesses, and disputes end before they turn into losses.
5. Compliance and Audits
Problem:
The state sends men to look at the books. They do not care about intent. They care about paper. A lender must prove every dollar taken, every interest charge added, and every letter sent down the road. If a clerk forgets to log a notice or a balance change, the record breaks. A broken record invites fines. Fines eat profit, and an auditor with questions is a hard man to satisfy.
Solution:
Good installment loan management software records what a man did and when he did it. Every payment leaves a track. Every changed address stays in ink on the screen. The machine forces the clerk through the proper gates before he touches an account, so nothing gets skipped. When the examiners pull up a chair, the file is clean and whole. The system keeps the memory straight, but keeping the operation clean remains the lender's burden.
6. Scaling Loan Servicing Without Increasing Manual Work
Challenge:
It is never the portfolio that grows. With it, servicing also gets affected. And so does the work required to service loans. When an applicant submits an application, and this is not about a single applicant, teams have to spend hours on recurring payment transactions and account maintenance. Yes, manual intervention may help for smaller portfolios. But when it comes to scaling, it becomes harder to sustain the pressure with every new loan application. Some immediate consequences of such discrepancies are: Delayed processing time; time spent on less trivial tasks.
Solution:
With its automated workflows, installment loan management software accurately manages portfolio growth. The software gathers all the relevant data, updates the dashboard, and gives lenders insights into what is working and what is not. In many modern installment loan management systems, teams do not have to go through multiple spreadsheets to make sense of the numbers. The software highlights failed transactions or payment discrepancies on its own.
Key Features to Look for in Installment Lending Software
Not every platform supports the same servicing requirements. Lenders should evaluate these capabilities before choosing Installment Lending Software.
Flexible Repayment Scheduling: Check whether the system supports different loan terms, interest calculations, payment frequencies, and schedule adjustments.
Payment Processing Integrations: Verify compatibility with existing payment processors. The platform should support transaction updates, failed payment handling, and reconciliation.
Delinquency Monitoring: Look for clear visibility into overdue balances, days past due, and account-level repayment status.
Automated Servicing Workflows: Assess which routine tasks can be automated. Make sure employees can review exceptions and intervene when needed.
Reporting and Analytics: Evaluate the available reports for outstanding balances, payment performance, delinquency trends, and portfolio activity.
Audit Trails and Access Controls: Confirm that the system records account changes, tracks user activity, and restricts access based on employee roles.
The right installment loan management software should fit existing operations and support future portfolio growth.
How Installment Loan Management Software Improves Lending Operations
Besides daily servicing tasks, Installment lending software plays a significant role in other areas. These include, but are not limited to, cost management, loan performance, and portfolio evaluation.
Lower Servicing Costs
The software helps teams spend less time on routine tasks and more on what needs more scrutiny. So your job isn't to spend hours correcting errors or updating accounts. It is to do what further the lending process: human judgment, performance analysis.
Better Portfolio Visibility
Lenders gain a clearer picture of repayment performance, overdue accounts, and outstanding balances. This helps managers identify problems and make informed servicing decisions.
More Consistent Borrower Experience
Accurate payment records and timely communications reduce confusion over balances and due dates. Borrowers can receive more consistent account information throughout repayment.
Greater Operational Control
Defined workflows and clearer responsibilities help lenders manage larger portfolios. Teams can track servicing activities, address exceptions, and maintain accountability as loan volumes increase.
Choosing the Right Installment Loan Management Software
Understanding the lending operations beforehand is paramount. If you don’t really understand what forces drive lending, no amount of software can undo the damage that has already been done. So, knowing how lenders operate always comes first.
This is where Infinity Software's installment loan management software comes into play. Rather than relying on a generic solution, lenders need a flexible platform that aligns with their lending criteria, supports their loan products and repayment structures, and adapts to their operational requirements.
Integration, moreover, is another consideration. The accurate exchange of information is a must. A well-developed installment loan management software maintains accurate information in payment processors, lending systems, and servicing records.
Lenders and fintech operators must understand the difference between what matters to them and what others are shifting to. Because only looking for more features and not matching the software with your own lending requirements is a recipe for disaster.




 <